What Does a Charter Operator’s Insurance Certificate Cover?
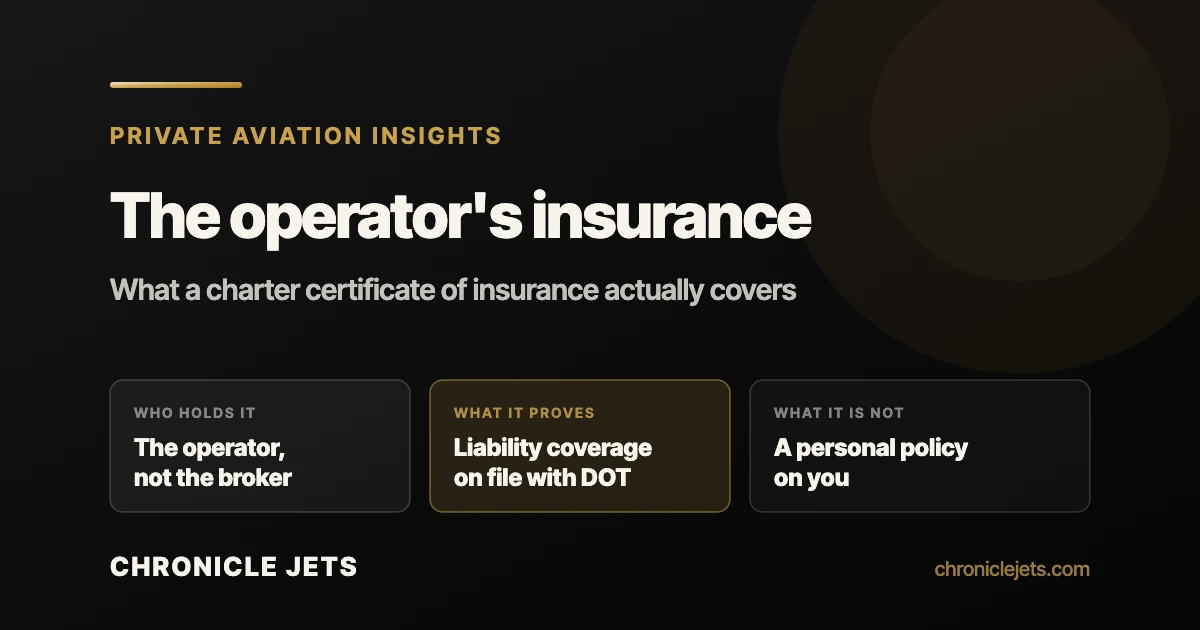
It proves the operator flying you carries aircraft accident liability insurance that meets federal minimums. That coverage pays claims for injury or death of passengers and other people, and for damage to other people’s property, caused by the operator’s flights. The certificate names the insurers, their limits, and the aircraft covered. It is not a personal policy on you.
TLDR:
- The operator, the direct air carrier in operational control, holds the required liability insurance. The broker does not.
- The certificate names each insurer, its limits, and which aircraft the policy covers.
- Operators file it with the Department of Transportation on OST Form 6410.
- For air taxi operators, the federal floor is $75,000 per passenger, set by 14 CFR 205.5.
- The coverage protects the operator against its liability. It is not travel or accident insurance on you.
- A broker must tell you, before you sign, what insurance it holds covering you, if any.
If your company’s travel or risk team wants proof of insurance before approving a charter, the operator’s certificate of insurance is the document to ask for. It is easy to read it as a promise that you are covered. What it actually proves is narrower, and worth knowing before you sign.
Ask us who operates your flight before you book
Who Holds the Insurance on a Brokered Charter Flight?
The short answer is the operator. On a brokered charter, two companies are involved, and federal rules put the liability insurance requirement on the one that flies the aircraft.
Under 14 CFR 205.3, a direct air carrier may not engage in air transportation unless it has aircraft accident liability coverage in effect. An on-demand charter operator that flies smaller aircraft typically registers as an air taxi operator, and 14 CFR 298.3 requires it to keep that coverage and a current certificate of insurance on file with the Department.
Chronicle Jets is an air charter broker. We are not a direct air carrier and do not have operational control of any aircraft. Every flight we arrange is provided by a properly licensed direct air carrier, and that carrier holds its own insurance. Our guide to how a broker differs from an operator covers the split in more detail.
Where the FAA certificate fits
The insurance requirement comes from the Department of Transportation’s economic rules, not from the FAA’s safety rules. The operator’s FAA certificate, explained in our Part 135 charter rules guide, covers pilots, training, and maintenance. The two travel together, and the next section shows what the insurance half looks like on paper.
What the Certificate of Insurance Actually Shows
A certificate of insurance is a summary, not the policy itself. Federal rules spell out what it has to contain, which tells you what to look for.
Under 14 CFR 205.3, the certificate must:
- Show each insurer providing the coverage, and when there is more than one, the limits and types of liability each one carries.
- List the aircraft covered, by type or class, by FAA registration number, or state that the policy applies to all aircraft the carrier operates.
- Be signed by an authorized officer, agent, or representative of the insurer or the insurance broker.
- Come from an insurer licensed in a U.S. state or territory, an approved surplus line insurer, or an insurer approved by a foreign government.
The operator files it with the Department on OST Form 6410, per 14 CFR 205.4. The same rule says an aircraft may not be listed on the operator’s FAA operations specifications, or flown, unless liability coverage is in force. The current certificate must also be available for public inspection at the carrier’s principal place of business.
That is what the document proves. The next question is how much coverage the rules require it to show.
The Federal Minimums, in Plain Numbers
The amounts below are legal floors, not typical limits. They come straight from 14 CFR 205.5, and they differ by the type of carrier.
| Coverage required | Air taxi operator (Part 298) | Other U.S. and foreign direct air carriers |
|---|---|---|
| Each passenger | $75,000 | $300,000 |
| All passengers, per aircraft, per occurrence | $75,000 x 75% of passenger seats | $300,000 x 75% of passenger seats |
| Each non-passenger, per occurrence | $75,000 | $300,000 |
| All non-passengers, per aircraft, per occurrence | $300,000 | $20,000,000, or $2,000,000 for aircraft up to 60 seats or 18,000 lb payload |
| Damage to property of others | $100,000 per occurrence | Included in the per-aircraft total above |
Which column applies depends on the aircraft. Under 14 CFR 298.3, an air taxi operator does not use large aircraft, which the rules define as more than 60 seats or more than 18,000 pounds of payload. An aircraft at or under both limits can be flown by an air taxi operator. A charter on a corporate airliner for a large group may be flown by a carrier with broader authority and the higher limits.
A worked example
An operator can meet the minimums with one combined single limit per occurrence. The rule’s own footnote shows the math for a 16-seat aircraft and lands at $1,300,000. Run the same formula for an 8-seat jet and the floor is $850,000.
The certificate shows what this operator actually carries, which is the number that matters. If the figure on your certificate is close to the floor, that is worth a question. If the figure is not shown at all, ask for it.
Get a quote with the operator named in writing
What the Certificate Does Not Cover
Knowing the gaps matters as much as knowing the limits. Three of them are worth understanding before you fly.
It is not a policy on you. The required coverage pays sums the carrier becomes legally obligated to pay. Federal rules treat it as deceptive for a broker or an air taxi operator to suggest passengers are directly insured when the only insurance protects the carrier, under 14 CFR 295.50 and 14 CFR 298.90. Personal travel or accident coverage is a separate purchase.
It does not set a minimum for the aircraft itself. The Part 205 minimums cover injury, death, and damage to the property of others. Coverage for damage to the aircraft is a matter between the operator and its insurer, so ask the operator if it matters to you.
It is tied to the operator’s authority. The required minimums apply to air transportation the carrier provides under its authority from the Department. That is one more reason to confirm the operator and the aircraft before you fly, as our questions to ask before booking walk through.
Protections Written Into the Policy
The rules also limit what an insurer can quietly take away. These protections sit behind every compliant certificate, even though they rarely appear on it.
- No safety-violation exclusion. Under 14 CFR 205.6, a policy may not exclude coverage because the carrier violated a safety rule. The insurer can still seek repayment from the carrier.
- Not tied to the carrier’s finances. Coverage cannot depend on the carrier’s solvency or freedom from bankruptcy, and a payment for one occurrence does not reduce coverage for another, per 205.5.
- Notice before it lapses. Under 14 CFR 205.7, a policy cannot be canceled, reduced, or allowed to expire until 10 days after written notice reaches the Department.
- No insurance, no flying. 14 CFR 298.37 bars an air taxi operator from offering or operating flights that its insurance does not cover.
Those rules are the reason a current certificate is worth asking for. Here is how to read the one you receive.
How to Read a Certificate Before You Fly
A certificate only helps if it matches your trip. Five checks cover the basics.
- The named insured matches the operator. Compare it with the corporate name of the carrier the broker disclosed for your flight.
- The aircraft on your trip is covered. Look for its type or class, its registration number, or a statement that the policy covers all aircraft the carrier operates.
- The policy dates cover your trip. A certificate that expires before your return leg needs an update.
- The limits are stated. Read the per-passenger and per-occurrence figures, or the combined single limit, against the minimums above.
- It is signed. A representative of the insurer or the insurance broker signs it, per 205.3.
This is general information, not legal or insurance advice. Confirm coverage details with the operator and its insurer, and have your own risk adviser review the certificate if your company requires it. For how operators are screened beyond insurance, see our private jet charter safety standards.
What a Charter Broker Owes You on Insurance
Brokers have an insurance disclosure of their own, separate from the operator’s certificate. It is one of the three disclosures owed before you sign.
Under 14 CFR 295.24, a broker must disclose the existence or absence of liability insurance it holds covering the charterer, passengers, and property, and the monetary limits of any such insurance. It must also name the carrier in operational control. If a required disclosure comes too late, you can cancel and receive a full refund.
Ask the broker for both items: its own insurance disclosure and the operator’s certificate. On a light jet trip for a small group or a larger charter, the paperwork works the same way.
Common Questions About Charter Operator Insurance
These questions cover what an operator’s certificate means for you as a passenger. The short version: the operator holds it, and it proves liability coverage, not personal coverage.
Does a charter broker carry the insurance for my flight?
Not the required liability coverage. Federal rules put that requirement on the direct air carrier operating the aircraft. A broker must disclose, before you sign, any liability insurance it holds covering you, and the limits, or that it holds none. That disclosure is separate from the operator’s certificate, so ask for both.
What is the minimum insurance a charter operator must carry?
For an air taxi operator under 14 CFR 205.5, the floor is $75,000 per passenger and $75,000 times 75% of the passenger seats per aircraft per occurrence. Non-passengers are covered at $75,000 each, up to $300,000, plus $100,000 for property damage. Larger carriers face higher minimums.
Does an operator’s insurance cover me personally?
No. It protects the operator against claims it becomes legally obligated to pay, such as injury caused by its flight. Federal rules call it deceptive to suggest passengers are directly insured when the only coverage protects the carrier. If you want personal accident or travel coverage, buy it separately.
Can I see a charter operator’s certificate of insurance?
Yes. Federal rules require the operator’s current certificate of insurance to be available for public inspection at its principal place of business, and the operator files it with the Department of Transportation. Ask your broker to request a copy, and check that it names the operator and the aircraft on your trip.
What happens if an operator’s insurance lapses?
The operator cannot legally fly. An air taxi operator may not offer or operate flights its insurance does not cover, and the Department can cancel its registration if coverage lapses. Policies also require 10 days’ written notice to the Department before cancellation or a reduction in coverage.
Does Chronicle Jets operate the aircraft?
No. Chronicle Jets is an air charter broker, not a direct air carrier, and does not have operational control of any aircraft. Every flight we arrange is provided by a properly licensed direct air carrier, which holds its own insurance, and we tell you which carrier operates your flight before you book.
Book with the operator and coverage in writing